Australian Internet Loans
Personal & Business Loan Information, Tools & Resources
Australian Internet Loans :: Articles

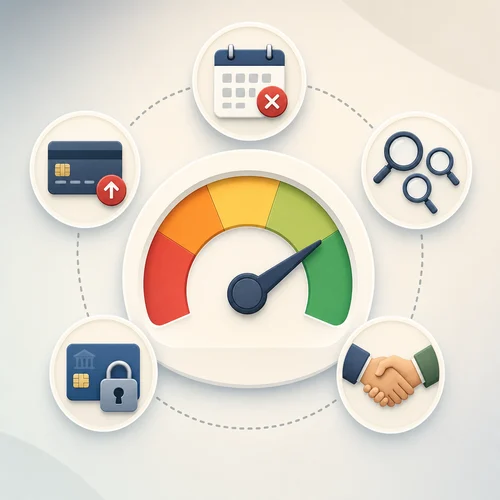
5 Credit Killers

What are the top factors that can damage your credit score?

5 Credit Killers

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

A good credit score speaks volumes about your financial habits. It's the evidence most creditors need to evaluate your credit worthiness.
Interestingly, there are some credit killers that even people maintaining good credit scores would unwittingly be a part of, which will be their undoing when applying for credit facilities in the future.
These mistakes may seem to be insignificant, but when the time comes, you may face more problems than you expect.

Avoiding Debt

Creditors need to evaluate your financial history to approve any credit facilities.
If you have no previous or existing debts, it might adversely affect your case, as creditors have no way of checking out how you'll handle the credit you get from them.

Shopping For Rates

Looking around for the best rate may actually turn out to be bad.
Too many inquiries within a short period could damage your credit score.
Usually, if you do more than 3 or 4 inquiries within a single month, you are likely to scare the lenders. For the same reasons, transferring the balances on your credit cards could be a bad idea as well.

Assuming There's a Grace Period

If you are late on a payment by even one day, you are late, period.
Never assume there's a grace period for late payments, because it only affects your credit score negatively.

Closing Old Accounts

Because your relevant transaction history also gets erased when you close your old accounts, your credit history is shortened and it may lower your credit score.
If you want to close your old accounts, close everything except the oldest account, which will leave a longer history.

Co-signing Loans

The obvious problem here is that the primary borrower's mistakes will end up on your credit report as well.

Australian Internet Loans Weekly News Insights

Podcast Cover Image This week: mortgage stress rises while most borrowers remain in positive equity ahead of the RBAs 3 November meeting; tax complaints to the Ombudsman surge 74%, with ATO interest and debt collection a growing pain point for self‑employed and PAYG borrowers; tens of thousands of drivers will receive CTP insurance refunds; and retailers seek extra finance before Christmas, a reminder for small businesses to plan cash flow and have documents ready for lenders. Episode includes practical prompts to check calculators, understand comparison rates and fees, and keep ATO statements current. Dated Saturday, 31 October 2026.

Published: Sunday, 1st Aug 2021
Author: Paige Estritori

Rate this article

0 Comments

No comments yet. Be the first to share your thoughts.


Finance News

Why the September Rate Rise Changes Loan Planning
28 Oct 2026: Paige Estritori
The Reserve Bank of Australia’s 29 September 2026 decision to lift the cash rate by 25 basis points to 4.60 per cent has put borrowing costs back at the centre of household and business planning. While the cash rate is not the only factor behind loan pricing, it influences funding costs and can flow through to variable rates, new fixed-rate offers and lender appetite for risk. - read more
Why Car and Equipment Borrowers Should Check the Final Payout
16 Sep 2026: Paige Estritori
Recent vehicle finance commentary has put balloon and residual payments back in the spotlight, particularly for Australians considering cars, utes, vans, trucks or business equipment. The issue is not that balloon structures are inherently unsuitable. Used carefully, they can help borrowers manage cash flow by lowering regular repayments. The risk is that the smaller monthly figure can distract from the larger amount still payable at the end of the loan or lease term. - read more
Why Selective Rate Cuts Deserve a Closer Look
09 Sep 2026: Paige Estritori
Recent lending market coverage points to a more competitive spring for Australian borrowers, with some banks and non-bank lenders adjusting selected fixed and variable loan offers. The shift does not mean borrowing has suddenly become easy or cheap, but it does suggest lenders are again competing harder for well-prepared applicants with stable income, clean repayment histories and clear loan purposes. - read more

Finance Articles

5 Key Steps to Take Before Applying for an Online Loan
Applying for an online loan can be a convenient way to manage your finances from the comfort of your own home. With technology's advancement, borrowing money has shifted from traditional brick-and-mortar institutions to digital platforms, making the process quicker and more accessible. However, navigating through this online landscape requires an understanding of how it operates. - read more
Common Pitfalls in Online Loan Applications and How to Avoid Them
Applying for a loan online has become a standard practice in today's digital world. It offers the convenience of applying from the comfort of your home, swift processing, and quick disbursements. However, the online loan application process is fraught with potential pitfalls that could hinder your chances of approval or lead to less favorable terms. - read more
How Vehicle and Equipment Finance Works for Australian Businesses
Vehicle and equipment finance can help Australian businesses access cars, utes, trucks, machinery or tools without paying the full purchase price upfront. This guide explains common structures, costs, assessment factors and questions to ask before applying. - read more